All Categories
Featured
Essential Tips for ESG Compliance in Commercial Landscapes
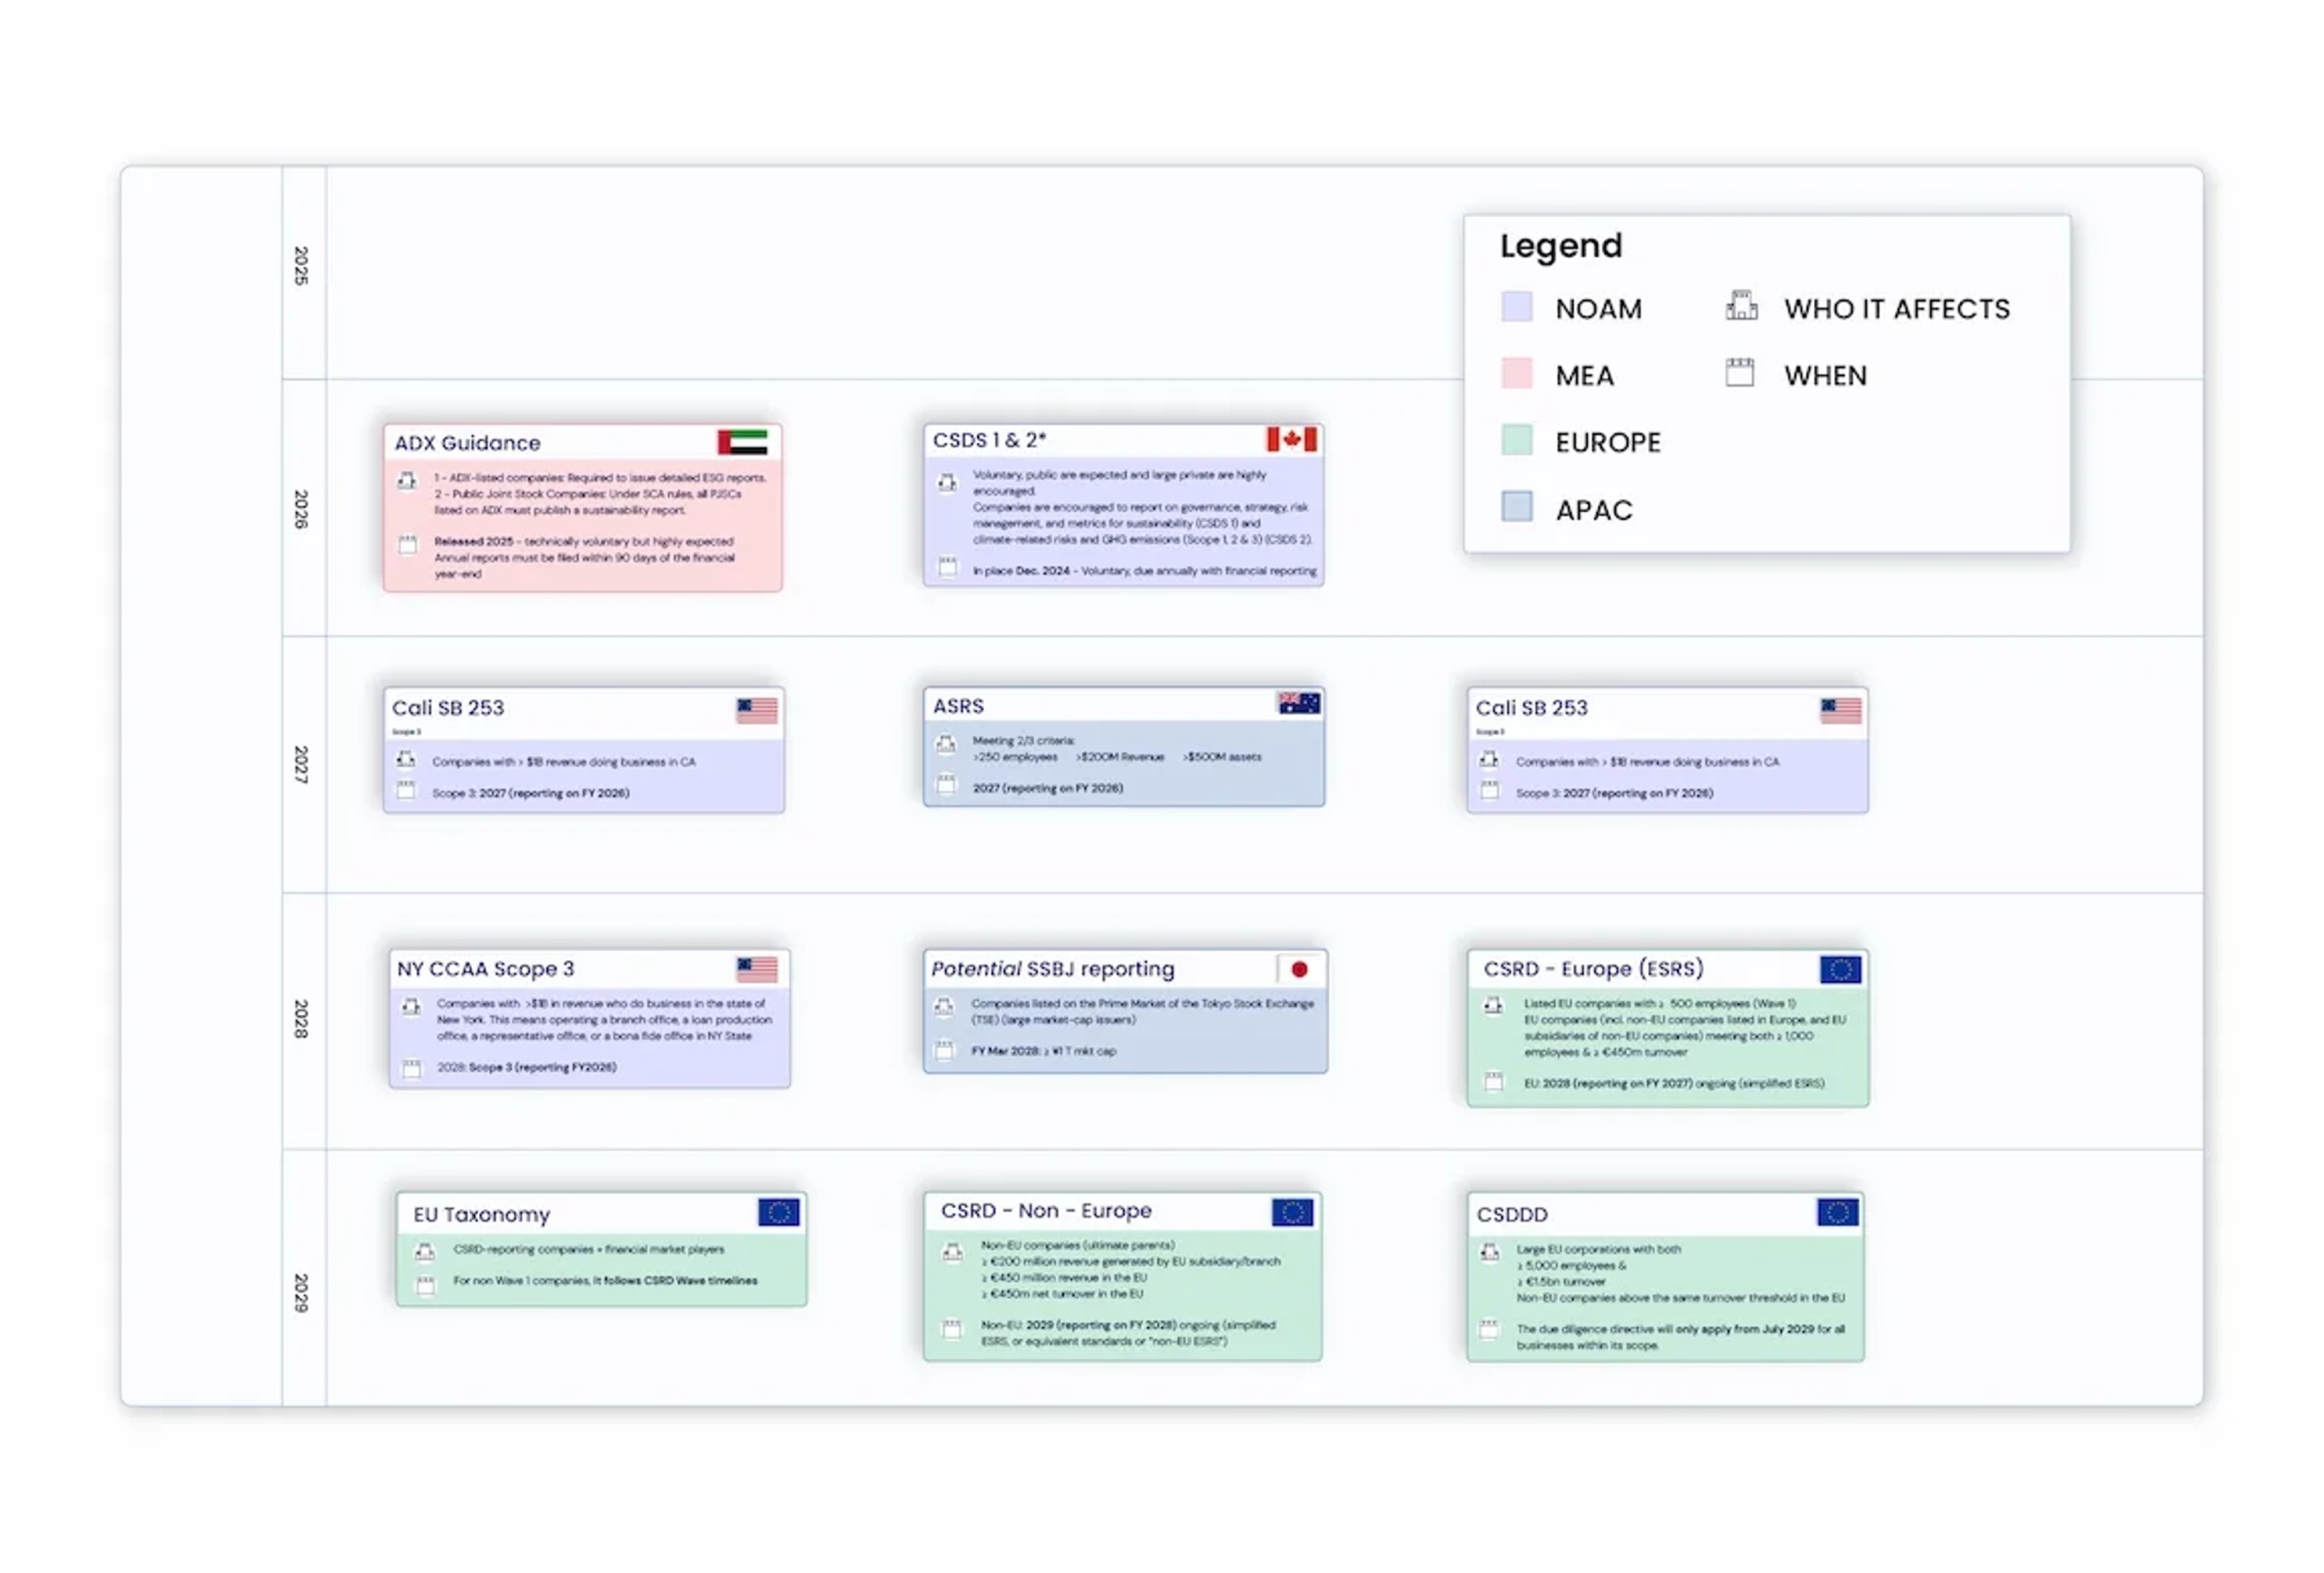
The rules apply to large companies doing organization in the state, with limits depending on the statute. The practical repercussion is that even where federal ESG politics stay contested, big companies can not presume hold-up everywhere.
Construct one core reporting architecture anchored in ISSB ideas, then map outside to ESRS, GRI, California, and sector-specific requirements. Deal with assurance preparedness as a 2026 build concern, not a 2027 clean-up exercise. Digitise sustainability data collection, controls, and tagging early, specifically where SME or value-chain data will be pulled upstream.
Translate regulative deadlines into board-level choices now, since reporting calendars for 2026 and 2027 are currently being set by regulators, not by internal convenience. The genuine trend, then, is not simply more frameworks. It is a more fully grown disclosure market. ESG reporting in 2026 and 2027 will be more assembled at the top, more requiring in execution, more auditable, and less flexible of weak data.
Those that wait will discover that the reporting obstacle is no longer writing the narrative. It is constructing the system behind it.
Last updated: April 8, 2026ESG data and sustainability metrics are forming how enterprises run, report, and manage business sustainability. As disclosure requirements expand across structures such as CSRD and IFRS S2, companies are under increasing pressure to produce reputable, audit-ready data across financing, operations, and supply chains. This guide combines the crucial sustainability statistics for 2026, covering enterprise adoption, reporting challenges, carbon accounting, and the growing expectations from financiers and regulators.
Comparing Traditional and Sustainable Landscaping Standards
76% of executives say sustainability is main to organization strategyOnly 1 in 5 finance groups presently report on their business's ESG metrics47% of financiers cite ESG data coverage gaps as their most significant challenge41% report data quality concerns, and 40% emphasize disparities across vendors84% of S&P 500 companies now identify environment modification as a financial threat, a significant boost from 67% in 202196% of G250 companies report on sustainability (the same given that 2022)85% of financiers say greenwashing claims have actually ended up being a more major problem than they were five years ago58% of financiers are making regulation-aligned ESG data a priority57% of businesses say client and financier expectations are the primary motorist of ESG strategyScope 3 emissions represent up to 7090% of overall corporate emissionsWorldwide ESG properties under management are forecasted to reach $40 trillion by 2030 Sustainability is now embedded in core business decision-making.
Broadening disclosure requirements and investor analysis are forcing organisations to standardise how sustainability information is collected and reported. 57% state investor expectations are the main driver of ESG strategy55% say regulation is a crucial influence on sustainability strategy58% of investors prioritise regulation-aligned ESG dataThe variety of nations with compulsory ESG disclosure requirements is anticipated to double1170% of supply chain professionals anticipate increased ESG openness demands11There are over 7,000 climate laws, policies and UNFCCC submissions9Regulation and investor expectations are now specifying the standard for how ESG information is gathered, structured, and disclosed, and sustainable investing is here to remain.
Numerous organisations do not have constant methodologies, centralised systems, and reputable procedures for collecting and verifying sustainability data. This produces considerable barriers to audit-ready reporting and investor confidence. 47% of investors mention ESG data coverage spaces as their most significant challenge41% report information quality concerns, and 40% emphasize inconsistencies across providers76% of executives mention data quality as a leading ESG reporting challenge60% of finance leaders battle with fragmented ESG data throughout systemsOnly around 20% of financing teams currently report on ESG metricsLess than 30% of organisations feel confident in the accuracy of their ESG dataThe restriction is no longer awareness, but the ability to produce constant, audit-ready sustainability data.
Expanding disclosure requirements and investor scrutiny are forcing organisations to standardise how sustainability data is collected and reported. 57% say investor expectations are the primary chauffeur of ESG strategy55% say guideline is a crucial influence on sustainability strategy58% of financiers prioritise regulation-aligned ESG dataThe number of nations with obligatory ESG disclosure requirements is expected to double1170% of supply chain experts anticipate increased ESG openness demands11There are over 7,000 environment laws, policies and UNFCCC submissions9Regulation and investor expectations are now defining the standard for how ESG data is collected, structured, and disclosed, and sustainable investing is here to stay.
Many organisations lack constant methodologies, centralised systems, and trustworthy processes for gathering and confirming sustainability information. This produces considerable barriers to audit-ready reporting and financier confidence. 47% of financiers mention ESG information coverage spaces as their greatest challenge41% report data quality issues, and 40% highlight disparities across providers76% of executives cite information quality as a leading ESG reporting challenge60% of financing leaders battle with fragmented ESG data across systemsOnly around 20% of financing groups currently report on ESG metricsLess than 30% of organisations feel confident in the accuracy of their ESG dataThe constraint is no longer awareness, but the ability to produce constant, audit-ready sustainability information.

Latest Posts

Improving Sustainability Through Green Methods

Why Switch Towards Eco-Friendly Business Grounds?

Utilizing Regional Service Centers for Broad Property Maintenance